Budget & pre-approval plan
We turn your income, savings and credit into a real monthly number, including taxes, insurance and HOA, then introduce two or three lenders who work with first-timers.
From "can I even afford this?" to keys in your hand. We translate the mortgage math, find the down payment help you qualify for, and negotiate like it's our own first home.
First Key Miami is a buyer's real estate agency in Miami, Florida that works only with first-time home buyers. We guide renters from pre-approval to closing on condos, townhomes and single-family homes across Miami-Dade County, and help them use Florida and county down payment assistance programs.
Minimum down payment on an FHA loan. Some conventional loans go as low as 3%.
Maximum Florida homestead exemption off your home's taxable value each year.
Days from accepted offer to closing on a typical financed Miami purchase.
Deadline to file your homestead exemption with the Miami-Dade Property Appraiser.
Everything a seasoned buyer already knows, handed to you in plain English. You bring the questions; we bring the checklists, the numbers and the negotiating.
We turn your income, savings and credit into a real monthly number, including taxes, insurance and HOA, then introduce two or three lenders who work with first-timers.
We screen you for Florida Housing, Hometown Heroes and Miami-Dade County programs up front, so you know what help you qualify for before you fall for a home.
Roof age, AC age, impact windows, flood zone, parking, pet rules. We point out the things that change your monthly cost, not just the countertops.
Comparable sales, seller motivation and smart terms. We negotiate price, repairs and seller-paid closing costs, the concession first-timers forget to ask for.
Budgets, reserve studies, milestone inspection reports and pending special assessments, read before you offer, so a $30,000 surprise never arrives after move-in.
Inspector, wind mitigation report, insurance quotes, appraisal and title, coordinated on one shared timeline. Then we remind you to file your homestead exemption.
Six steps, usually two to four months from first call to keys. You'll always know which step you're on and what's coming next.
We talk budget, savings, credit, must-haves and timing. You leave with a written plan and a realistic price range.
30 minutesA lender verifies income and credit and issues a pre-approval letter. We line up any down payment assistance and the required homebuyer education course.
About 1 weekYou sign a written buyer agreement, then we tour homes that fit both your list and your budget, with private notes on each one.
4–12 weeksWe price it with comparable sales, set your escrow deposit and inspection period, and ask for seller credits toward closing costs.
1–5 daysHome inspection, a wind mitigation report and insurance quotes happen inside your inspection period, when you can still renegotiate or walk away.
Usually 10–15 daysAppraisal, final loan approval, a final walk-through, then you sign with the title company and get your keys. Homestead filing comes next.
30–45 days after offerBrickell gets the headlines, but most first homes in Miami-Dade are bought a few miles away. These are the areas our clients ask about most.
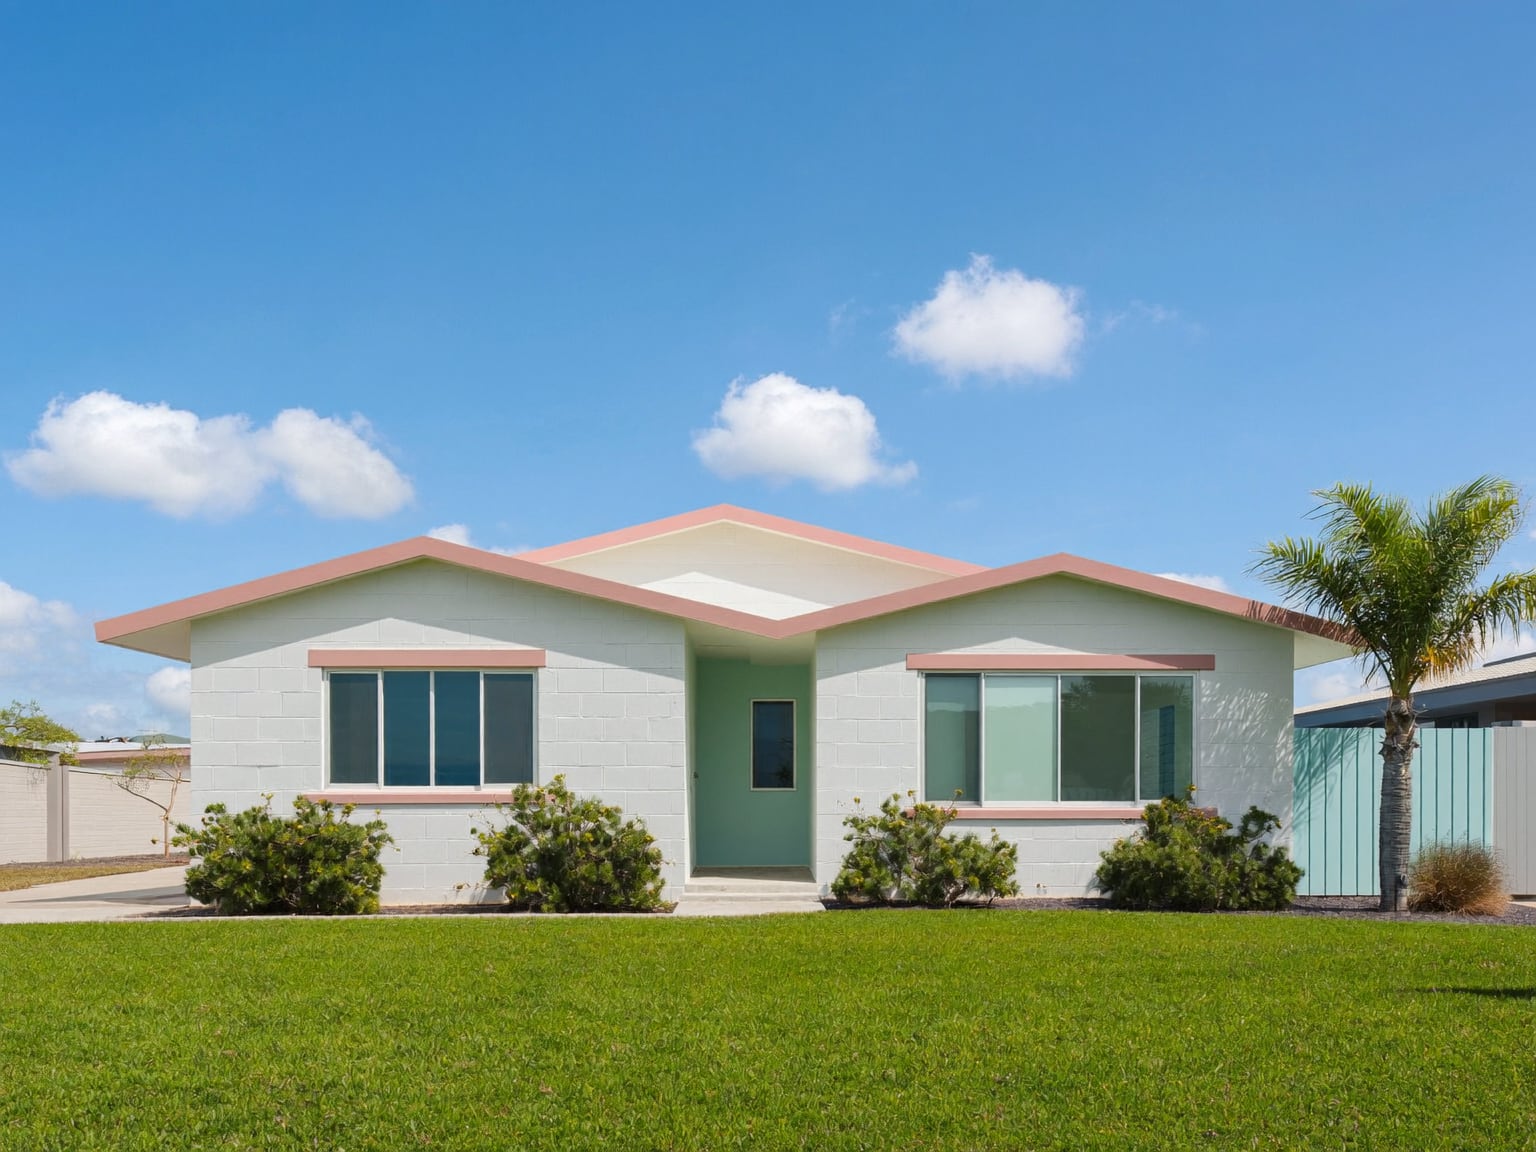
Condos · Ranch-style houses
Mid-century houses on real yards, quick access to Biscayne Boulevard and FIU's Biscayne Bay campus. A favorite for buyers who want a house, not just a unit.
Watch for: flood zone and roof age on older homes.
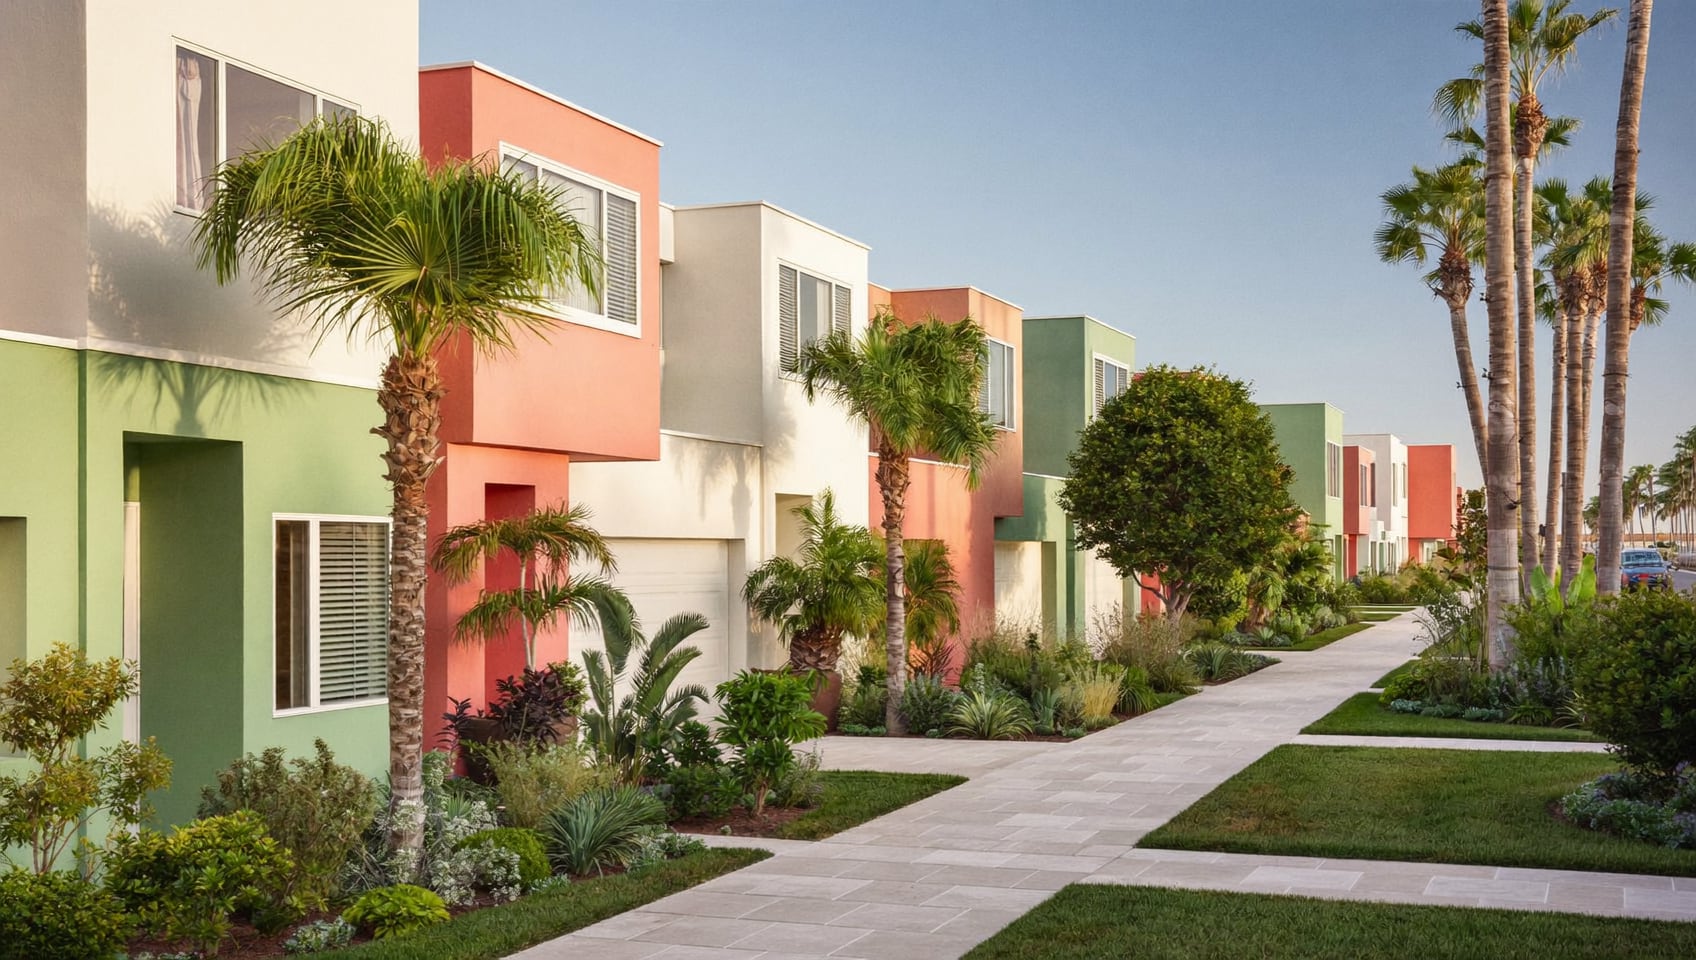
Townhomes · Condos · Family homes
Big supply of townhomes and garden-style condos, strong schools and Dadeland shopping. Metrorail at Dadeland makes downtown commutes painless for many buyers.
Watch for: HOA rules and monthly dues that vary widely from community to community.
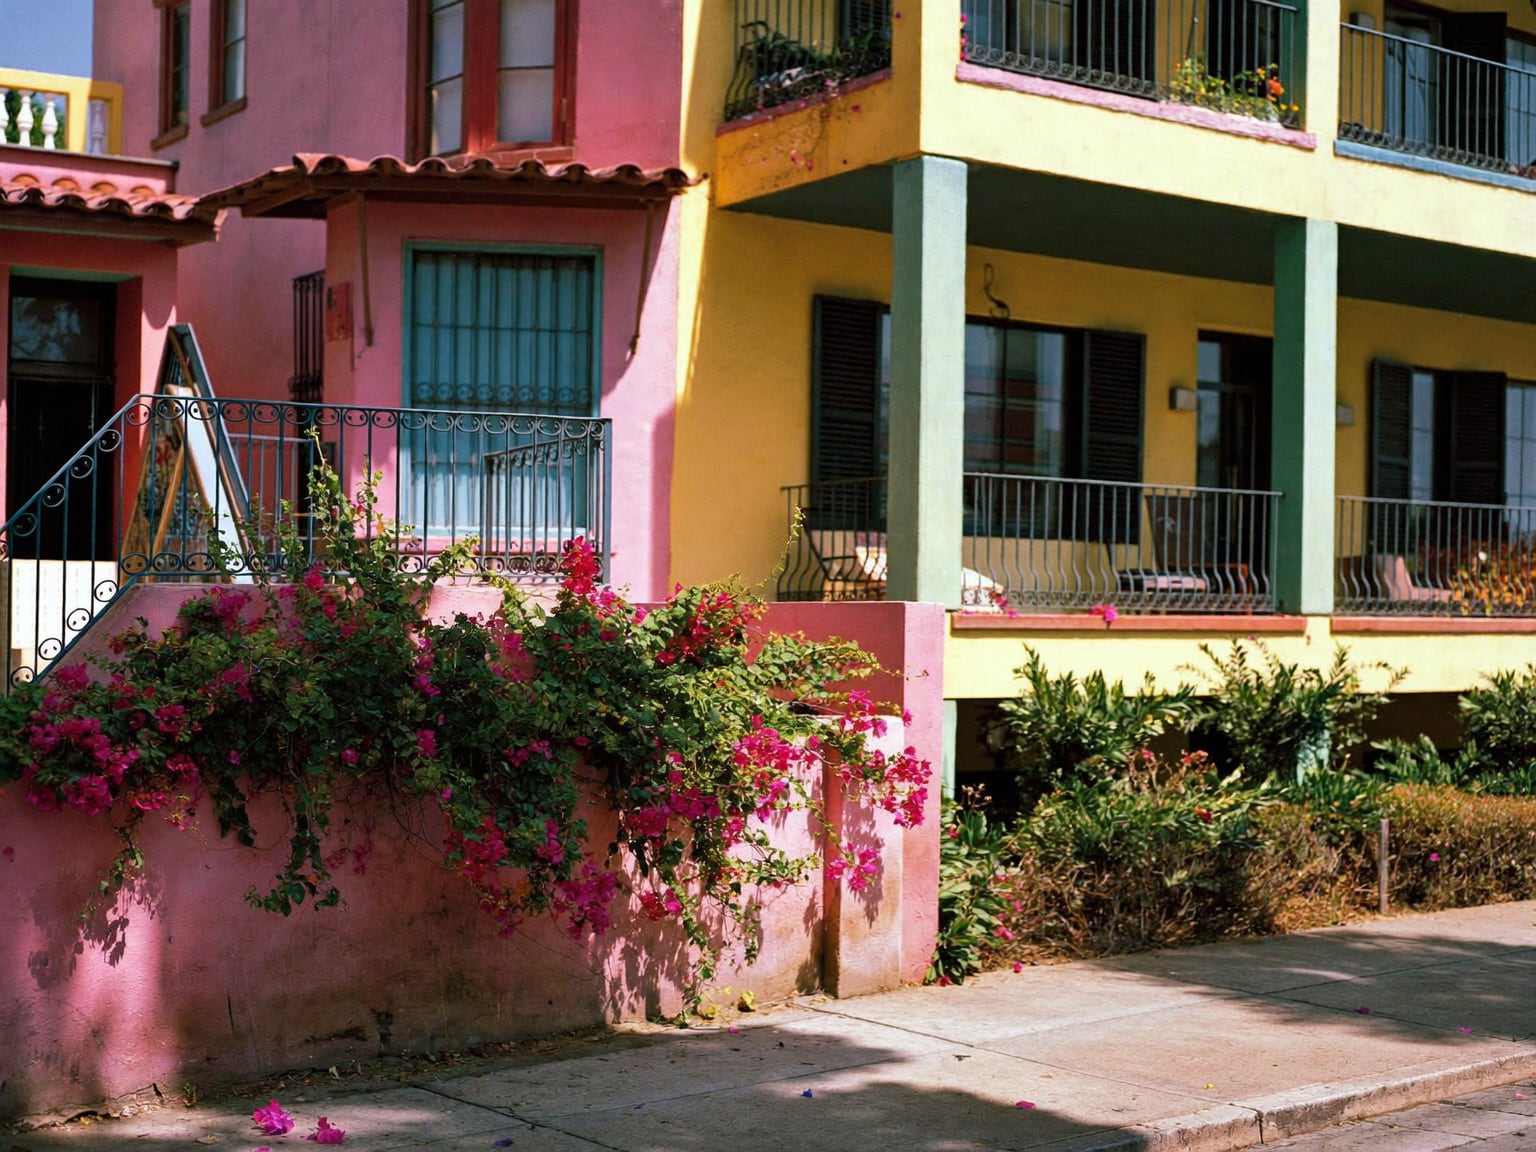
Condos · Small multi-family
Walkable, central and full of character. Some buyers use FHA to purchase a duplex, live in one side and rent the other.
Watch for: older building systems and condo reserves.
Houses · Newer condos
Minutes from the Health District and Wynwood, with a growing arts scene and still-reachable prices compared with its neighbors.
Watch for: block-by-block variation; we compare sales street by street.
Single-family houses
Quiet, established streets near FIU's main campus and the Palmetto. Concrete-block homes from the 1950s and 60s that hold up well.
Watch for: original electrical and plumbing updates.
New-construction houses · Townhomes
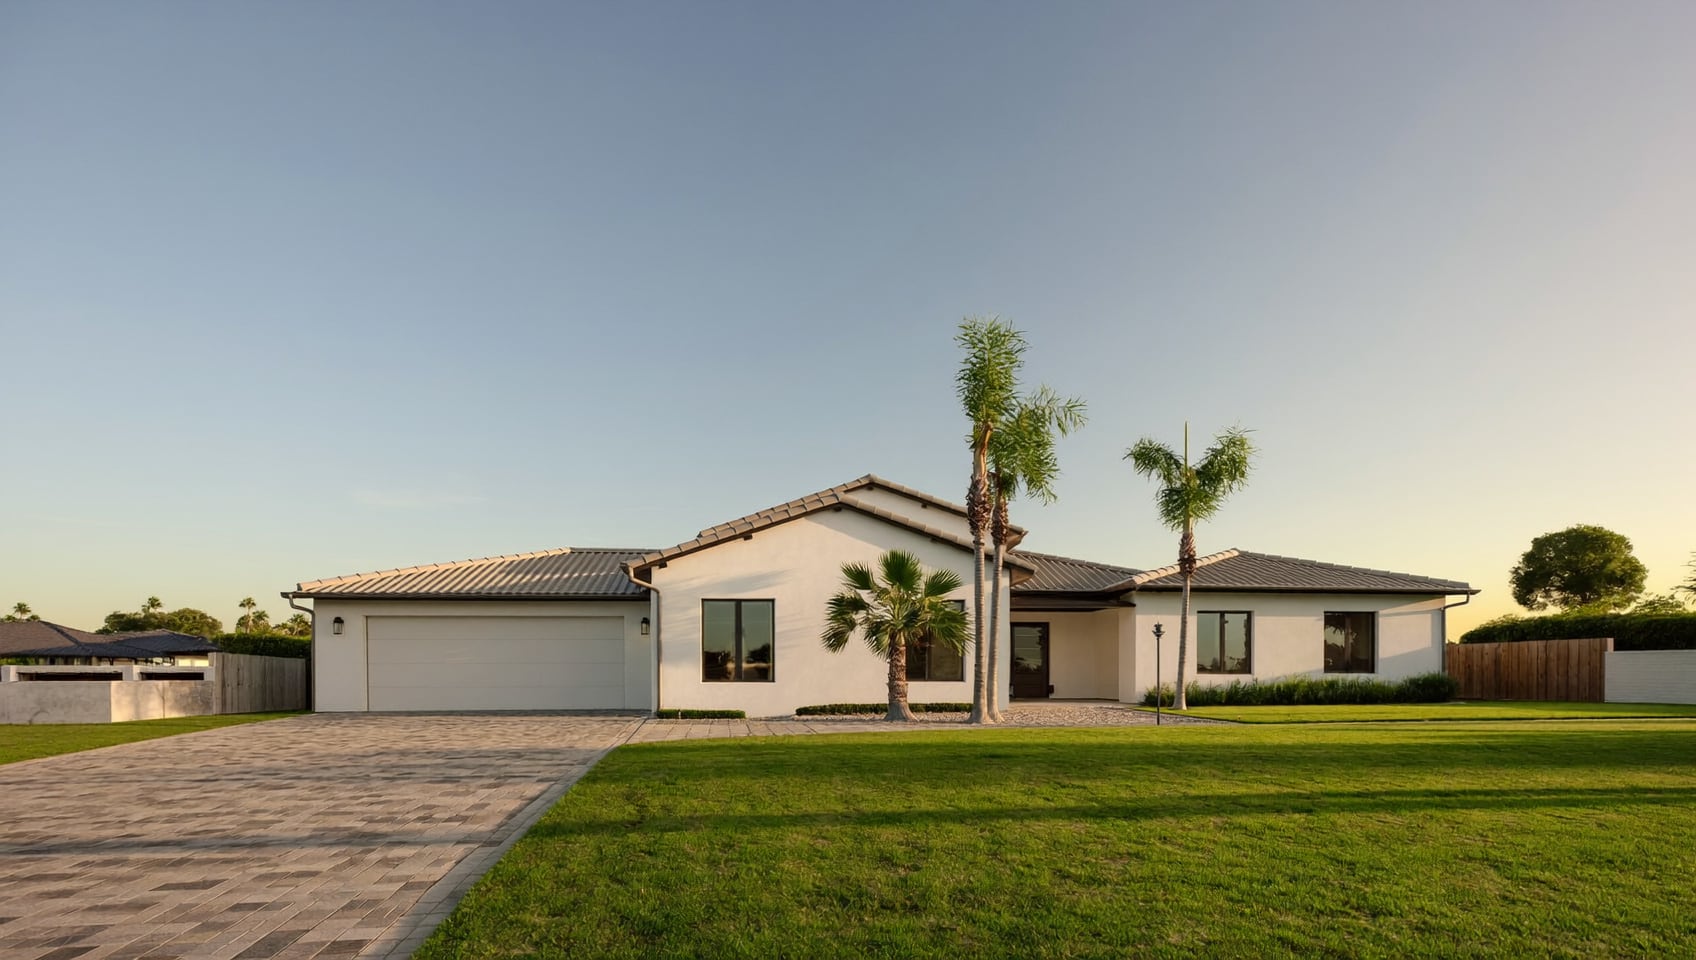
The most space for your money in Miami-Dade, including newer homes built to current Florida Building Code with impact windows that can lower insurance. Ideal if you work south or remotely and want a yard, a garage and room to grow.
Watch for: commute time on the Turnpike and CDD fees (a special taxing district fee) in some new communities.
Budget tiers are relative within Miami-Dade and change with the market. Ask us for current sold prices in any neighborhood.
Less than most renters think, but more than just the down payment. Here's what "cash to close" means and what usually goes into it.
Illustrative estimate before any assistance or seller credits.
| What matters | Condo | Townhome | Single-family house |
|---|---|---|---|
| Purchase price | Usually the lowest entry point | Middle of the range | Usually the highest |
| Monthly fees | Highest; dues cover building insurance, reserves and amenities | Moderate HOA dues | Often none, unless in an HOA or CDD community |
| Your insurance | Lower; you insure the interior (an HO-6 policy) | Varies by association coverage | Highest; you insure the whole structure |
| Maintenance | Association handles roof and exterior | Shared; you handle your interior and often your roof | All yours: roof, AC, yard, pool |
| Key risk | Special assessments from milestone inspections and reserve funding | HOA rules on rentals, pets and parking | Big-ticket repairs and flood-zone exposure |
| Best for | Lowest upfront cost and lock-and-leave living | More space with less upkeep | Yards, pets, privacy and long-term equity |
Because your first purchase is a different job. Fewer assumptions, more explanation, and a lot more attention to the monthly budget than to the listing photos.
Add a short quote from a real customer here.
Add a short quote from a real customer here.
Add a short quote from a real customer here.
The questions we hear on almost every first call. Don't see yours? Ask us directly; it's free.
Ask your questionMost first-time buyers need 3% to 3.5% of the price, not 20%. An FHA loan requires 3.5% down and some conventional loans allow 3%. On a $400,000 condo that is $12,000 to $14,000, and Florida and Miami-Dade assistance programs can cover part of it for buyers who qualify.
Your first strategy call is free, and our fee is agreed in writing before you tour any home. Since August 2024, buyers sign a written agreement first. In many Miami deals the seller covers some or all of the buyer agent fee through negotiated concessions, so your out-of-pocket cost is often small.
Yes, several programs offer down payment and closing cost help to qualifying Miami-Dade buyers. Options include Florida Housing Finance Corporation loans, the Florida Hometown Heroes program and Miami-Dade County assistance. Eligibility depends on income, price and a homebuyer education course, and we connect you with lenders who use them.
It depends on your budget, but condos are often the most affordable entry point if the building is financially healthy. Since Florida's 2022 condo safety laws, older buildings must complete milestone inspections and fund reserves, which can mean special assessments. We review budgets, reserves and inspection reports before you offer.
Most buyers close 30 to 45 days after an accepted offer. Before that, getting pre-approved takes about a week and touring usually runs four to twelve weeks. Buyers using down payment assistance should plan for the longer end, since program approvals add extra paperwork and review time.
It reduces the taxable value of your primary residence by up to $50,000 and caps yearly assessment increases at 3%. You qualify if you own and live in the home as your permanent residence on January 1, and you apply with the Miami-Dade Property Appraiser by March 1.
Insurance is one of Miami's biggest ownership costs, so get quotes before you commit. Premiums depend on the roof's age, wind mitigation features like impact windows, and the FEMA flood zone. We gather quotes during your inspection period so a surprise premium never derails your budget or loan approval.
Thirty minutes, no pressure, no credit check. You'll leave knowing your realistic price range, the assistance you may qualify for, and your next three steps, whether you buy this year or next.
Your request is in. Expect a reply within one business day to pick a time for your strategy call.